Integrity One

Your Complete Financial Solution

  • Home
  • News
  • Services
    • Financial Planning Services
    • Aged Care
    • Finance & Mortgage
    • Centrelink & DVA
    • Accounting & Taxation
    • Business Advisory Services
    • Planning for Success
    • Gen X,Y & Z
  • Small Business Portal
  • About Us
    • Our Team
    • Financial Services Guide
  • Contact Us

5 tips to pay off your mortgage faster

January 3, 2024

Can you imagine living mortgage-free? For many homeowners, mortgage repayments represent a large part of their salary and many years of hard work, with the end not clearly in sight.

Whether your goal is to soon be mortgage-free or to reduce your mortgage to allow you to renovate, invest or live more comfortably, there are things you can do to make this a reality. And it may be simpler than you think, with a few small changes you can make now.

Make more frequent repayments

The first tip is an obvious one – to make more frequent repayments towards your mortgage so that you can pay it off sooner. What may not be apparent though is that this can be easier to do than you may think.

If you are currently making monthly repayments, consider switching to fortnightly repayments. By doing so, you can end up making the equivalent of an extra month’s repayment every year, given that there are 26 fortnights in a year. Keep in mind though that this only works if the fortnightly repayment is half that of the monthly repayment, so it depends on how your loan payments have been calculated.

There are home loan repayment calculators online, such as www.moneysmart.gov.au, that can help you crunch the numbers.

Increase your regular repayments

Another way to get ahead on your mortgage and work towards paying it off sooner is to pay a little extra each month or fortnight on top of your minimum repayment.

While this may be more challenging with higher interest rates at the moment, but rounding up your repayments or if you are able to find a lower interest rate paying your previous repayment amount will chip away at your principal repayment and reduce the interest you pay over the life of your loan.

Make additional lump sum repayments

As with the previous tip, by making extra repayments you will reduce the interest you pay and shorten the life of your loan.

These repayments can come from obvious sources, such as your tax return or a bonus, or may come from even such small wins, such as selling an item online – however you are earning a bit of extra money. Do you have a birthday coming up and think there may be a monetary gift? Even making small extra repayments can help chip away at the loan.

Open an offset account

Opening an offset account – a savings or transaction bank account linked to your home loan – is worth considering in order to pay off your mortgage sooner. Interest is then charged on the difference between your home loan balance minus the amount you have in your linked offset account.

Once you have an offset account, you can get your salary paid into it directly so that there will always be money in the account, working to reduce the interest you pay.

You will need to check with your lender as to whether your loan is eligible for an offset account, and if so, if 100% of the balance can be offset against the home loan.

Revisit your home loan

It may also be worthwhile revisiting your home loan and considering whether it’s still fit for its purpose. Read back over your loan’s terms as a starting point to refamiliarise yourself with them.

By considering your goal of paying off your loan sooner, you might see room for improvement, or the need to refinance or switch to a different lender. You might also find that you are paying for features you aren’t using – for example, if you do have an offset account but are not using it, you still might be paying an annual fee for it.

There are also small changes you can make, such as changing the loan type, or frequency of payments.

There’s no doubt that paying off your home loan does involve work, but by keeping these things in mind, you may be mortgage-free sooner than you think. So that we can support you to get there, contact us today to ensure you make the most of great rates and have a loan that suits your financial situation.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522
Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

Quarterly property update – Dec 2023

December 4, 2023

A slow and steady race to the 2023 finish line

Whichever way you look at it, the Australian property market is finishing the year on a fairly even keel. Values are on a slight upward trajectory, but it’s clear the head-turning price jumps of the recent past are now in the rear view mirror.

CoreLogic’s national Home Value Index (HVI) has reported a quarterly increase of 2.1%, but a monthly movement of just 0.6% – the smallest monthly gain since the growth cycle commenced in February. As December begins, the median dwelling price in Australia now sits at $753,654, up on the same time last year at $714,475.

Over the past three months the combined capitals figure just edged out the combined regions rising 2.2% to $827,659 compared with a 1.8% rise to a median of $602,645. A year ago, the capital median was $778,368 while the regional median was $578,506.

November shows a V-shaped recovery

Although prices have experienced a notable slowdown, CoreLogic’s national HVI reached a new record high in November. After a peak to trough fall of -7.5% between April 2022 and January 2023, housing values bounced 8.3% in just 10 months – what CoreLogic’s research director Tim Lawless said demonstrated a clear ‘V’ shaped recovery.

Figures show Perth with its 5.4% rise in values, as well as Adelaide and Brisbane both experiencing a 3.9% jump, are the clear quarterly standouts. Mr Lawless cited low stock levels as the reason behind the positive price performances. “This imbalance between available supply and demonstrated demand is keeping strong upwards pressure on housing values across these markets, despite the downside factors leading to weaker housing market conditions across the lower eastern seaboard,” he explained.

On the other hand, Darwin had the most negative quarter with a subtle -0.7% decline, Hobart only inched up 0.1% while Melbourne and Sydney moved by 0.6% and 1.8% respectively. “The Melbourne Cup day rate hike has clearly taken some heat out of the market, but other factors like rising advertised stock levels, worsening affordability and persistently low consumer sentiment are also acting as a drag on value growth in some markets,” Mr Lawless said, while adding Sydney home values had slipped into negative growth during the last week of November which could push Harbour City prices back by early 2024.

Luxury end looking lacklustre

Top end markets across our nation’s most expensive cities appear to be experiencing a wind down. CoreLogic reported seeing slower growth conditions across the upper quartile for Sydney and Melbourne as the priciest quarter of those markets is now showing the lowest rate of growth both on a monthly and rolling quarterly basis. This could be a sign of things to come. Historically, how the most expensive markets in Sydney and Melbourne track gives an insight into the future performance of the wider market.

“As borrowing capacity reduces, we may be seeing more demand deflected towards lower housing price points, with the broad middle of the market now recording the strongest rate of growth in Sydney and Melbourne,” Mr Lawless said.

Interest rate impact

Despite what was a surprise rise in the cash rate in November, PropTrack data shows national home prices have so far defied interest rate pressures. In fact, values lifted to a record high in November according to the PropTrack Home Price Index by REA Group.

Eleanor Creagh, senior economist at PropTrack, said although national home price growth slowed in November, spring offered increased choice for buyers. “Strong housing demand, buoyed by record net overseas migration, tight rental markets, low unemployment and home equity gains, has worked alongside limited housing stock to offset the impacts of higher interest rates this year,” she said.

“Despite interest rates climbing again in November and the flow of listings hitting the market increasing, housing demand has remained strong and national prices have now risen for 11 straight months.”

Whether the RBA will introduce yet another hike when it meets next week remains to be seen, but all signs point to a positive start to 2024 according to Ms Creagh.

“Looking ahead, price growth is expected to continue as the positive tailwinds for housing demand and a slowdown in the completion of new homes counter the sharp deterioration in affordability and slowing economy. However, prices are likely to lift at a slower pace than they have across 2023.”

Dwelling values over the quarter

Melbourne
Although the quarterly movement was 0.6% for all dwellings to a median price of $779,914, values are up 3% annually. The highest annual dwelling change was in the SA3 of Monash where there was an annual increase of 7.9% to a median of $1.247 million. Investors looking at the Victorian capital can expect an average gross rental yield of 3.4%.

Sydney
The Harbour City saw values increase by 1.8% over the quarter to a median of $1.125 million, but annually values are still up 10.2%. The Marrickville/Sydenham/Petersham SA3 in Sydney’s inner west saw the greatest dwelling value growth at 14.4% to $1.694 million. The average gross rental yield for Sydney is 3%.

Brisbane
Queensland’s capital experienced a healthy quarter of 3.9%, but a significant annual increase of 10.7%. Dwellings in the Nathan SA3 experienced the highest growth for the year to October 31 with a jump of 15.1% per cent. The median dwelling value in Brisbane is $779,270 and the average rental yield in the city is 4%.

Canberra
The median dwelling price in Canberra is still the second priciest in the country at $842,677 after a quarterly change of 1.1%, but an annual decrease of -0.3%. Molongo’s dwelling price increased 5.5% annually to $758,556 making it the highest performing suburb in the nation’s capital. Currently, rental yields in the city are at 3.9%.

Perth
The West Australian capital is still home to some of the cheapest metropolitan property in the country with a dwelling median of $646,520 (only behind Darwin’s $496,792). Values rose 5.4% over the past quarter and the annual growth is sitting at 13.5%. Perth’s rental yield is 4.6% and the suburb of Armadale saw the greatest annual change with a rise of 21.5% to a median of $551,197.

Note: all figures in the city snapshots are sourced from: CoreLogic’s national Home Value Index (December 2023)

To find out how you might be able to purchase a property in the current market, reach out to your trusted broker today.

If you have any questions or need any information please give us a call on 039723 0522.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522
Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

A loan when you don’t tick all the boxes

October 9, 2023

It can be difficult to think about a property purchase if you don’t meet all the criteria for a loan. Perhaps you work for yourself, have recently moved jobs, taken time out of the workforce to raise a family, or your credit history isn’t squeaky clean.

Rest assured that there are still loan options to suit your circumstances, which a broker is well positioned to help you access. Here is the rundown on some options you might not have considered.

Non-conforming loans

Non-conforming loans are suited to people whose situations aren’t clear cut and therefore are likely to face barriers when applying for traditional loans. They provide an opportunity for people with irregular incomes – such as freelancers, those at the end of their careers or who are returning to the workforce – to access financing.

Low documentation loan

One type of a non-conforming loan is known as a low documentation (low doc) loan. These are geared towards people who are self-employed – who have an income and assets, but who may not have all the documents usually required for a loan (such as years of tax returns and income statements).

Instead, a self-verification process is in place, where you sign a declaration stating your earnings. As the name low doc suggests, the reduced documentation needed for these type of loans enables borrowers who wouldn’t usually be able to provide the required information to access a loan.

It’s a misconception with this type of loan that you don’t have to provide any documents, however. As well as submitting an income declaration form, you will likely also need to provide your bank statements and a letter from your accountant that confirms your financial standing. You may also be asked for your ABN, a BAS statement and GST registration details, if applicable.

For those who are self-employed, keep in mind you may still be eligible for a traditional loan. While low doc loans were initially designed for small business owners and self-employed, if you have the necessary financials and tax returns available for assessment you could still be successful in a full doc loan application. We can help guide you and advise the best loan for your circumstances.

Signs you may not be a ‘perfect match’ for some of the lenders:

  • You have a solid income, but only have a small deposit
  • Your work means you regularly change jobs. This can imply you don’t have job stability, however for some it could just be the nature of your particular industry
  • You need to consolidate a few other debts such as personal loans, credit cards or business debt
  • You don’t have a perfect credit history. This may be that you have missed loan/ bill payments in the past or have previously declared bankruptcy
  • You have recently started a business or a new job
  • You are self-employed

Bad credit loans

It’s not the most appealing name, but this type of loan is geared towards people who have difficulty qualifying for a loan due to their credit score. It can also be an option for people with little to no credit history, for example those who have never had a credit card.

If you have a credit score of lower than 700, traditionally a bank would consider you too high a financial risk to approve. This type of non-conforming loan can help you access funds.

Generally, bad credit loans only allow you to borrow a small amount of money, so you’re unlikely to be in a position to make a big purchase, such as property.

Things to keep in mind

It’s also worthwhile knowing that non-conforming loans (including low doc loans) often come with higher interest rates than traditional home loans – this is because they are deemed riskier for the lender with a higher risk you not being able to make the repayments. Therefore, they may have a risk fee attached to them and there might also be stricter loan terms, such as larger deposits required.

Unfortunately, you may not be able to borrow as much as you would ordinally be able to with a traditional loan, so re-approval is key to ensuring you’re aware of how much you are able to borrow before making a purchase.

Another factor to consider is that as non-conforming loans aren’t very common, you’re likely to be limited in terms of your choice of lender. Finally, even non-conventional loans aren’t guaranteed – not all applications are successful.

What you will need

There is a common misconception that you don’t require much documentation for these types of loans, which is not the case. While your circumstances may be more complex than a straightforward application, you will need to be able to show your income and demonstrate the capacity to make the repayments for your potential loan.

As with a traditional loan, you’ll be required to complete an application form and, generally speaking, at a minimum you will need to provide a copy of your ID, bank statements and proof of income.

Finding the right fit

Non-conforming loans can be beneficial but they’re not the right choice for everyone. Having the assistance of a broker can help you navigate the different loan options and find the best fit for your circumstances.

If you don’t tick all the boxes when it comes to applying for a home loan, we can guide you through the loan application process and can help find the right solution for your circumstances.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522
Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

Tips to conquer house hunting fatigue

September 4, 2023

Buying a home takes time. Not so much the actual act of putting in an offer, having it accepted and waiting on settlement, which can take as long as the settlement period of 30 to 120 days. But the process that comes before all of that. The process of saving for, looking for, and buying your dream home.

Depending on what is happening in the market and where you are looking, it generally takes an average of nine months to locate a home to buy.

If you throw in the time it takes to come up with a deposit, your timeframe is a lot longer – often stretching out to many years. Even over a decade for some. That means it can be hard to keep the momentum going. Let’s look at some ways to manage what can at times feel like a never-ending journey.

Have some room in your budget for fun

If you’ve been saving for a deposit for a while, you might be feeling like you’ve been frugal forever! It takes a lot of discipline to come up with a decent deposit and there is always that little voice in your head thinking ‘if I only had a little more to spend’ that spurs you on to save even more.

While it’s important to stay on target with your savings it’s equally important when you are in for the long haul to have a little wriggle room to enjoy yourself and have some allowance for a planned splurge now and then.

Know what you are looking for

It can be overwhelming with the amount of stock on the market, and if you feel your life revolves around going to open for inspections you might need to narrow the field a little.

While it’s useful to attend auctions and opens to get a feel for the market and understand what is a realistic price rather than rely on price guides that can be underquoted, it’s frustrating spending time looking at unsuitable properties. They key is to narrow the field, so think about things like where you want to buy and the size, age and condition of the property.

Also consider what you are prepared to compromise on. A neighbouring suburb may offer better buying power than the suburb you have set your sights on, or you may wish to consider a slightly smaller or older property.

Equally there are some things that might be non-negotiable for you. You might want something built in the last decade and be prepared to look at smaller properties to get that or you want an inner-city pad to be close to work and are happy to consider older ‘renovator’s delights’ to get the location you are after.

Hold out for the right property

While it’s important to be flexible and distinguish between your ‘must haves’ and ‘nice to haves’, resist the temptation to buy a place that’s not quite right or exceed your budget to get the perfect property. It’s tempting to buy the next house you see so you can put all this stress and pressure behind you. However, you are likely to make multiple offers and be unsuccessful numerous times before you eventually succeed.

Remember that real estate agents are working for the vendor and if the terms are not to your liking or you are being pressured to make an offer that exceeds your budget or within an unreasonable timeframe, it’s OK to respond with a firm ‘no’. It can be a good idea to cultivate relationships with agents and let them know what you are after though, as they can do some of the legwork for you.

Take a break if you need to – it’s not a race and the odd weekend off might be just what you need.

Make sure you are ready when you find the right one

Finally, make sure you have your ducks in a row. Your most important duck – even before making a verbal offer – is knowing what you can borrow and having a pre-approval in place, and we can help with that. You’ll also need to think about conveyancing and building and pest inspections.

It can seem like a long journey, but you will get there! We are here to help you every step of the way.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522
Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

Quarterly property update – September 2023

September 4, 2023

Australia’s housing recovery gains momentum in August

Interest rates continue to be a hot topic of conversation among commentators, economists and mortgage holders. There is cautious optimism that rates are approaching stabilisation with rates remaining unchanged over the last two months of the quarter.

National growth back in the black

The CoreLogic National Home Value Index reached a milestone over the winter period, clawing back loses over the last 12 months to grow by 0.8% in August. The National HVI rose for the sixth consecutive month in August since bottoming out in February with growth broadly recorded across the country, the rate of growth increased again in August after the previous two-month trend slowing capital gains.

While the upper quartile of the market drove growth earlier in the year, the nation’s slowdown in the growth rate earlier in the quarter was largely being driven by easing gains in this segment of the market. There was, however, resilience in the middle and more affordable segments of the market, thanks to a bounce back from first home buyers and investors in recent months.

What impact are interest rates having?

Eleanor Creagh, Senior Economist at PropTrack shares that “stronger housing demand and a limited flow of new listings hitting the market have offset the impact of interest rate rises” over the quarter.

She believes with interest rates are nearing their peak, this will likely sustain current market confidence and maintain the lift in home values. However, she cautions, “the full impact of recent rate rises is yet to be felt, and the potential for further tightening remains a headwind for the market.”

Spring starts with a bang

The strong winter momentum looks set to flow into the spring selling season. Spring is set to start with a bang, with PropTrack data showing that the number of auctions scheduled for the first week of spring is up 13% compared to the same time in 2022.

PropTrack economist Anne Flaherty believes the unusually high number of auctions could be due to sellers holding off selling their properties over the first half of this year and late last year, a general improvement in selling sentiment and confidence increasing amid signs that interest rates may have peaked.

The influx of new properties hitting the market could be good news for buyers working to alleviate some of the competition.

Dwelling values over the quarter

The national Home Index Value grew by 2.5% over the quarter, with Brisbane leading the way. Within the capital cities, house values rather than unit values generally showed a sharper recovery trend.

Sydney
Sydney grew 3.8% over the quarter, with the Harbour City’s ongoing recovery now placing dwelling values at 1.2% higher over the last 12 months. Sydney’s monthly pace of growth has increased to 1.1% in August, with the rental yield holding relatively steady at 3.1%.

Melbourne
The Victorian capital continued its steady growth with 1.6% over the quarter, growth slowing slightly in August compared to July. The rental yield unchanged in August with 3.5% returns.

Brisbane
Brisbane led the growth for the nation’s capital cities in August with 1.5% growth and increasing by 4.2% over the quarter. In Brisbane, renters can take note of the 4.2% gross rental yield in August.

Canberra
Canberra recorded an increase of 0.5% over the quarter. After a decline in growth in July, dwelling values rebounded to grow by 0.3% in August. The nation’s capital has a current gross rental return of 4.0%.

Perth
Perth saw a 2.9% jump in values over the quarter, building on its annual growth of 4.5% and recording a new cyclical high through August. One of the few cities to do so. Investors will be happy with the country’s second highest gross rental return (behind Darwin) at 4.9%.

Note: all figures in the city snapshots are sourced from: CoreLogic’s national Home Value Index (September 2023)

If you have any questions or need any information please give us a call on 039723 0522.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522
Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

Is your mortgage still working for you?

August 14, 2023

A mortgage is a long-term commitment, one in which many people enter with a ‘set and forget’ mentality. Most loans are around 30 years – a long time in which many things can change, not just in your personal circumstances but in the financial world, seeing the introduction of new loan products and fluctuations in interest rates.

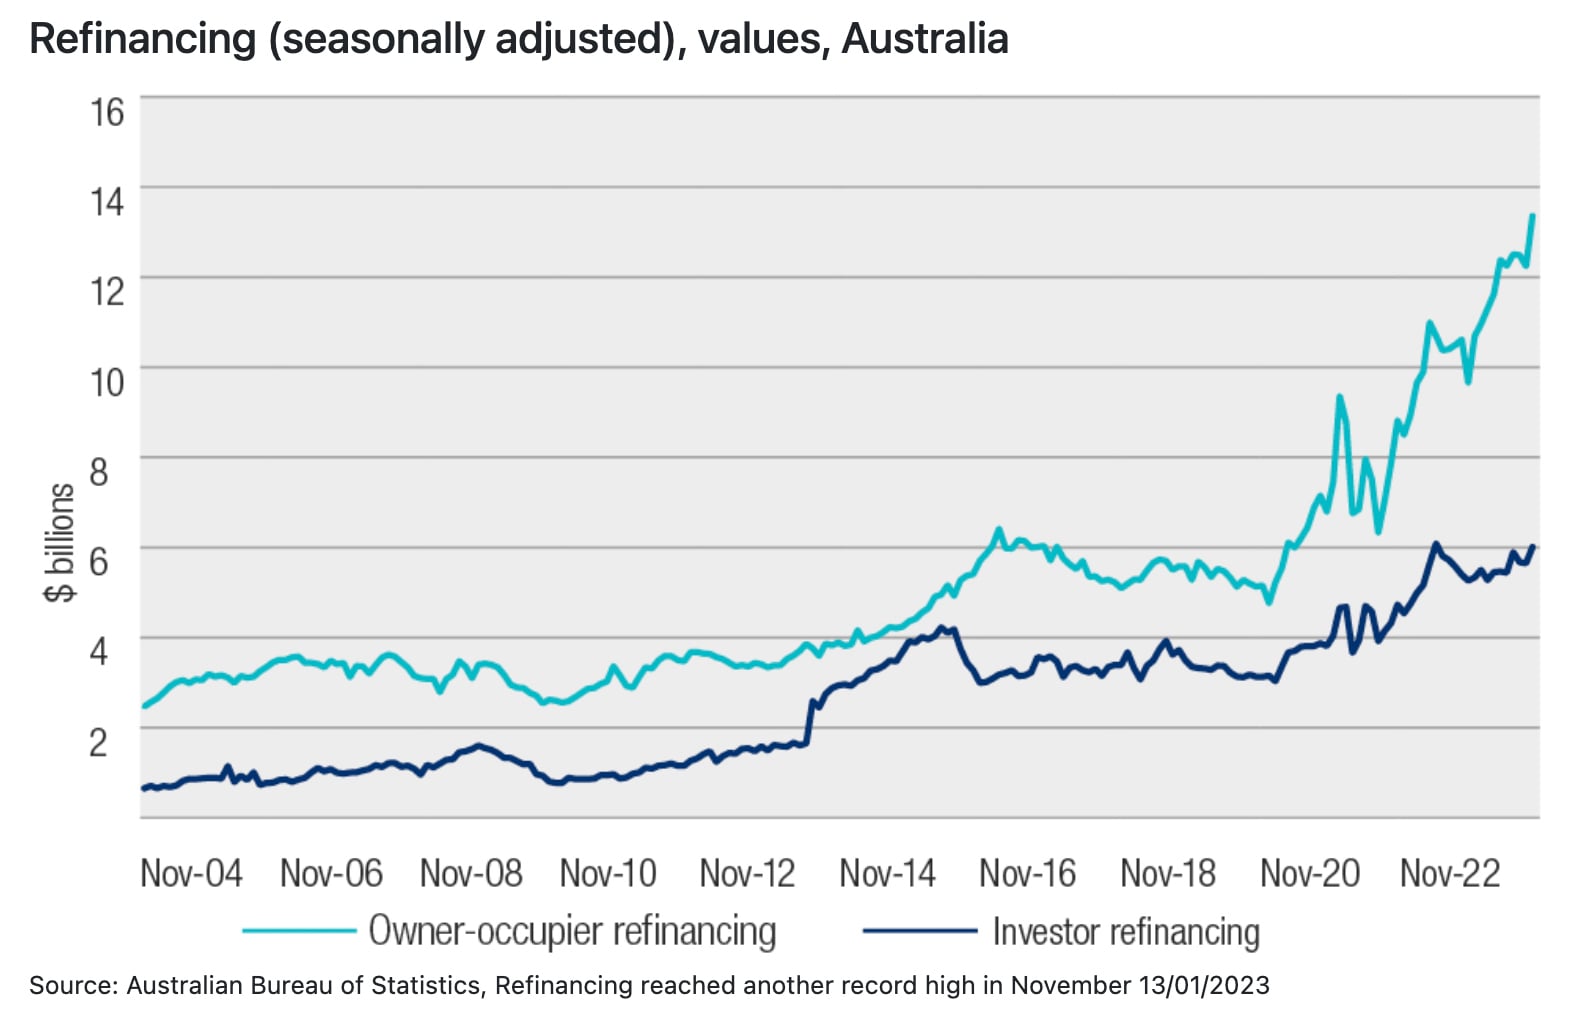
If you haven’t reviewed your loan for a while, now is a good time to consider whether it still suits your circumstances or whether you’re better off making some changes. It’s what many Aussies are doing, with the ABS reporting the value of owner-occupier refinancing of $13.4 billion last November.i

Reviewing your loan

It is a good idea to review your loan annually and there’s no better time than the present.

While this can seem like an arduous task, it doesn’t need to be complicated. Read back over your loan’s terms as a starting point. To ensure you’re receiving the best interest rate for your loan – and whether your loan is still fit for purpose – ask yourself a few things:

  • Has there been a change in your employment status?
  • Has there been a change in your family situation?
  • Have your financial goals changed?
  • Are there pressing matters that need financing (i.e. renovations, needing a new car, etc)?
  • Are you wanting to invest or change your existing investments?

Knowing where you are standing financially can help you then decide whether it’s worth refinancing and chasing a better interest rate, or whether your existing mortgage is still working for you.

Types of refinance loans

There’s not just one type of refinancing, but many different types of refinance loans, including:

Rate-and-term refinance loan

This is where you replace your loan with a new loan that is the same amount, but at a changed interest rate and/or term. This is the most common refinancing option and often what people think of when it comes to refinancing.

Cash-out/cash-in refinance

A cash-out refinance loan enables you to access the equity in your home by taking out a new loan with a higher loan balance than your existing loan.

A cash-in refinance loan has you lowering your overall loan amount by contributing a lump sum – this is done by taking out a new loan less than your old loan, paying out the difference to close your old loan.

Fixing your interest rate

As opposed to a variable rate, a fixed loan guarantees a locked interest rate for a period of time (usually between 1-5 years). This is a popular option during a time of rate hikes. However, it can come with drawbacks such as not being able to take advantage of any rate cuts.

Split loans

As its name suggests, a split loan allows you to split your loan into multiple parts with different interest rates and terms. For instance, you could have part of your loan at a variable interest rate and another part as a variable rate.

Consolidation refinance

This is where you combine all your various debts into the one debt (including credit cards, car loans, etc) and therefore one repayment. This can make your debts easier to manage but can mean your short terms debts are stretched over the life of your new home loan.

Things to keep in mind

While (generally speaking) the goal of refinancing is to save money, there are a few considerations to be aware of, so you don’t end up paying more in your quest to save.

Refinancing can impact your credit rating, causing it to drop. However, it’s worth keeping in mind that this dip is short-term and shouldn’t have too big an effect on your credit score in the future.

Another thing to be mindful of is that you may need to pay Lender Mortgage Insurance (LMI) again. As LMI protects lenders, your original LMI payment won’t cover a new lender, which is why you can expect to pay this again. For most borrowers, you’ll need 20% of the property’s current value to avoid paying LMI again, keep in mind the value of your property may have changed since you first took out your loan. You might also need to pay LMI even if you stick with the same lender, but you’ll likely be given a discount.

There are also costs related to refinancing, such as application fees, discharge/break fees and valuation fees. Some lenders waive these costs or offer a discount, so be sure to ask what you will be expected to pay and see what you can negotiate.

You may also find that your bid for refinancing is rejected if you have accumulated too much debt or if your living expenses are now too high. Changes to your loan could also stretch out the repayment period, leading you to pay more in the long run.

Keeping on friendly terms with your mortgage

Whether you decide to refinance or stick with your current loan, by refamiliarising yourself with the conditions of your loan and assessing your financial situation, you’ll be better placed than if you ‘set and forget’.

Set a reminder to do this once a year – it can be easier to remember come the end of the financial year or the start or end of the calendar year.

You don’t have to go through the process alone. Give us a call on 039723 0522 to discuss your existing loan and circumstances and to chat about your future financial goals.

Nicholas Berry Credit Representative Number 472439 is a Credit Representative of Integrity Finance (Aust) Pty Ltd – Australian Credit Licence 392184.
This information is of a general nature and does not take into consideration anyone’s individual circumstances or objectives. Financial Planning activities only are provided by Integrity One Planning Services Pty Ltd as a Corporate Authorised Representative No. 315000 of Integrity Financial Planners Pty Ltd ABN 71 069 537 855 AFSL 225051. Integrity One Planning Services Pty Ltd and Integrity One Accounting and Business Advisory Services Pty Ltd are not liable for any financial loss resulting from decisions made based on this information. Please consult your adviser, finance specialist, broker, and/or accountant before making decisions using this information.

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Email: integrityone@iplan.com.au

Telephone : 03 9723 0522

Integrity One Facebook

Integrity Edge Facebook

Filed Under: Blogs, News Tagged With: MB

  • « Previous Page
  • 1
  • …
  • 6
  • 7
  • 8
  • 9
  • Next Page »
  • Home
  • What’s News
  • About Us
  • Financial Services Guide
  • Contact Us

Services

  • Financial Planning Services
  • Aged Care
  • Finance & Mortgage
  • Centrelink
  • Accounting and Taxation
  • Business Advisory Services
  • Gen X,Y & Z

Recent News items

Market movements & economic review – November 2026

Ensure your estate planning reflects your wishes

Mastering AI: it’s all in the prompts

All News items

Contact Us

Suite 2, 1 Railway Crescent
Croydon, Victoria 3136

Phone: (03) 9723 0522

Find us on Facebook

  • Home
  • Sitemap
  • Privacy
  • Complaints
  • Contact

All Rights Reserved 2016 Copyright Integrity one